


In this article I will cover the Best SoFi Competitors for High-Yield Banking in 2026. I will be reviewing banks and financial institutions that provide competitive APYs, do not charge monthly service fees, and provide FDIC insurance. Some great alternatives to SoFi include, Ally Bank, Bask Bank, CIT Bank Platinum Savings, Western Alliance Bank, Wealthfront Cash Account, ETRADE Premium Savings, Marcus by Goldman Sachs, Synchrony Bank, Discover Bank, American Express HYSA,* and others.
What Are SoFi Competitors?
SoFi Competitors Offer products that compete more directly with SoFi’s high-yield savings accounts. Some competitors may offer a slightly higher APY, low or no fees, and FDIC insurance.
Traditional Banks that offer these accounts include: Ally Bank, CIT Bank, Western Alliance Bank, Synchrony Bank, and Discover. Some fintech competitors include: Wealthfront, Bask Bank, Marcus by Goldman Sachs, ETRADE Premium Savings, and American Express.
Each competitor attempts to gain an edge by including features such as a linked checking account, ATM access, promotional rates, or other linked financial service products. By doing this they attempt to attract consumers that prefer a more comprehensive financial services relationship.
Key Points
| Bank/Platform | Best For | Key Features |
|---|---|---|
| Ally Bank | Pure savings | No minimums, no fees, direct FDIC insurance |
| Bask Bank | Raw APY | No minimum deposit, simple structure |
| CIT Bank Platinum Savings | High-balance savers | Tiered APY, FDIC-insured |
| Western Alliance Bank | Consistent high yield | $1 minimum, FDIC coverage |
| Wealthfront Cash Account | Fintech hybrid | Brokerage-style features, FDIC via partner banks |
| E*TRADE Premium Savings | Short-term savers | 6-month promotional APY |
| Marcus by Goldman Sachs | Simplicity | No fees, strong institutional backing |
| Synchrony Bank | ATM access | Nationwide ATM network, FDIC-insured |
| Discover Bank | Customer service | 24/7 support, no balance caps |
| American Express HYSA | Existing Amex users | Seamless integration with Amex ecosystem |
1. Ally Bank
One of the largest online banks, Ally was founded in 2009. In 2026, they are expected to offer a high-yield savings account with an APY of 4.20%. Their high-yield savings account has no minimum balance, and therefore no monthly service fee. Unlike some of their competitors, Ally offers high-yield checking accounts.
Like their savings accounts, Ally’s checking accounts have no monthly service fee and no minimum balance. As a digital bank, Ally does not have physical locations. However, they have partnered with banks and other financial institutions to provide their customers with ATMs and reimburse Ally customers for out-of-network ATM transactions.
Because Ally does not have physical locations, they have a strong and accessible user-friendly mobile site. Like other banks, Ally provides FDIC insurance to their customers.
Ally Bank Features, Pros & Cons
| Feature | Pros | Cons |
|---|---|---|
| Founded | 2009 | Relatively new compared to legacy banks |
| APY (2026) | 4.20% (highest) | Rate may fluctuate with Fed changes |
| Minimum Balance | None | N/A |
| Monthly Fee | None | N/A |
| Checking | Available with bill pay | Online-only, no branches |
| ATM Access | Nationwide + reimbursements | Limited physical presence |
| FDIC Insurance | Yes, up to $250K | Standard cap only |
| Mobile App | Highly rated | No in-person service |
| Customer Service | 24/7 support | Digital-first only |
| Integration | Savings + checking seamless | No credit card ecosystem |
| Accessibility | Easy account opening | Online-only may deter some |
| Yield Stability | Consistently high | Dependent on market rates |
2. Bask Bank
Bask Bank began as a division of Texas Capital Bank in 1999, and has since offered a competitive annual percentage yield (APY) of 4.10% (2026) on its high-yield online savings account. Unlike other banks, Bask Bank doesn’t charge monthly fees or require a minimum opening balance, and currently has no checks or ATMs.
The bank is entirely online and focuses on providing its clients the highest yield for their savings. Bask Bank is FDIC insured and provides its clients the security of protecting their deposits up to $250,000. Its high-yield savings account is very simple, and offers its clients a higher yield than competitors that have complex accounts.
Unlike Bask Bank, SoFi has accounts that also require very little from its clients, however its yields aren’t as high as Bask Bank’s.
Bask Bank Features, Pros & Cons
| Feature | Pros | Cons |
|---|---|---|
| Founded | 1999 (Texas Capital Bank) | Less known nationally |
| APY (2026) | 4.10% | Slightly lower than Ally |
| Minimum Balance | None | N/A |
| Monthly Fee | None | N/A |
| Checking | Not offered | Savings-only |
| ATM Access | None | No physical withdrawals |
| FDIC Insurance | Yes, $250K | Limited to single bank |
| Mobile App | Simple, easy use | Fewer features |
| Customer Service | Online support | No branches |
| Focus | Pure yield | No ecosystem |
| Accessibility | Easy signup | Limited product range |
| Yield | High, no conditions | No tiered options |
3. CIT Bank Platinum Savings
Founded in 1908, CIT Bank has its Platinum Savings account with an APY of 4.10% (2026) for balances of $5,000 and above. For balances below this, the APY is lowered, making this account a better option for those with a higher balance.

CIT Bank has a lower opening deposit of $100, and no monthly fees. While ATM access is not available through this bank, customers are given the option to transfer money through linked checking accounts.
CIT Bank is online-only, and has stronger features for account management, compared to other banks. For higher balances, CIT Bank is a good option. It competes with SoFi, which also increases APY with balance requirements.
CIT Bank Platinum Savings Features, Pros & Cons
| Feature | Pros | Cons |
|---|---|---|
| Founded | 1908 | Legacy institution |
| APY (2026) | 4.10% (balances > $5K) | Lower APY if under $5K |
| Minimum Balance | $100 to open | $5K for top APY |
| Monthly Fee | None | N/A |
| Checking | Limited | Not full-service |
| ATM Access | None | Transfers only |
| FDIC Insurance | Yes | Standard cap |
| Mobile App | Functional | Less advanced |
| Customer Service | Reliable | No branches |
| Focus | High-balance savers | Not ideal for small deposits |
| Accessibility | Online account opening | Tiered APY complexity |
| Yield | Strong for large balances | Weak for small savers |
4. Western Alliance Bank
Founded in 1994, Western Alliance Bank offers a competitive 4.10% APY (2026) on high-yield savings accounts. The bank’s high-yield savings account has a low minimum balance of $1 and does not charge monthly service fees.
As an added benefit, Western Alliance Bank provides FDIC insurance on accounts up to $250,000. Like most banks, Western Alliance focuses its operations on the West Coast, but the bank has become more competitive digitally. With strong yields and flexible customer policies, Western Alliance Bank is one of the better banks to offer high-yield savings accounts.
Unlike other high-yield savings accounts, Western Alliance does not limit how often customers can make withdrawals. This feature, in addition to the bank’s consistent APY and low opening deposit, makes the bank a strong contender to SoFi, and other high-yield savings accounts.
Western Alliance Bank Features, Pros & Cons
| Feature | Pros | Cons |
|---|---|---|
| Founded | 1994 | Regional presence |
| APY (2026) | 4.10% | Limited national reach |
| Minimum Balance | $1 | N/A |
| Monthly Fee | None | N/A |
| Checking | Limited | Not widely available |
| ATM Access | Minimal | Mostly digital |
| FDIC Insurance | Yes | Standard cap |
| Mobile App | Available | Less robust |
| Customer Service | Regional support | Not nationwide |
| Focus | Low entry requirement | Limited ecosystem |
| Accessibility | Easy to start | Smaller footprint |
| Yield | Competitive | Less brand recognition |
5. Wealthfront Cash Account
Wealthfront began operations in 2008 and opened its Cash Account in 2020. Its Cash Account has a 4.00% APY (2026) compounding interest. The account has no minimum balance and charges no monthly fees.
Wealthfront is not a bank and does not hold depositors’ funds. Wealthfront has partnered with several FDIC-insured banks to offer insurance on deposits up to $250,000. Customers can link their Wealthfront Cash Account with Wealthfront’s investment account to initiate transfers and use other financial planning tools offered by Wealthfront.
Customers can withdraw funds by initiating a transfer to an external checking account. Wealthfront Cash Account provides a high interest yield and is a good competitor to SoFi in the cash account segment.
Wealthfront Cash Account Features, Pros & Cons
| Feature | Pros | Cons |
|---|---|---|
| Founded | 2008 | Fintech-only |
| APY (2026) | 4.00% | Slightly lower than Ally |
| Minimum Balance | None | N/A |
| Monthly Fee | None | N/A |
| Checking | Not offered | Savings-only |
| ATM Access | None | Transfers only |
| FDIC Insurance | Yes, via partner banks | Complex multi-bank setup |
| Mobile App | Advanced fintech tools | No physical presence |
| Customer Service | Digital-first | No branches |
| Focus | Hybrid savings + investing | No ATM withdrawals |
| Accessibility | Easy online signup | Tech-savvy users only |
| Yield | Strong | Not top-tier |
6. E*TRADE Premium Savings
ETRADE opened its first brokerage in 1982 and offers a Premium Savings account with a promotional 4.00% APY (2026) on the first $5,000 for a period of six months. Once the promotional period ends, the APY will be determined by ETRADE.

The account has no minimum balance, and there are no monthly fees. ETRADE has integrated brokerage and checking accounts. The Premium Savings account provides ATM access through a partner network. ETRADE reimburses customers for out-of-network ATM fees.
Deposits are FDIC-insured up to $250,000. The promotional APY and brokerage integration makes the Premium Savings account a good competitor to SoFi for the short-term cash segment.
E*TRADE Premium Savings Features, Pros & Cons
| Feature | Pros | Cons |
|---|---|---|
| Founded | 1982 | Long-standing |
| APY (2026) | 4.00% (promo 6 months) | Drops after promo |
| Minimum Balance | None | N/A |
| Monthly Fee | None | N/A |
| Checking | Available | Linked to brokerage |
| ATM Access | Partner networks | Limited reimbursements |
| FDIC Insurance | Yes | Standard cap |
| Mobile App | Strong brokerage integration | Focused on investors |
| Customer Service | 24/7 | Investment-centric |
| Focus | Short-term savers | Not ideal long-term |
| Accessibility | Easy online | Promo complexity |
| Yield | High intro | Lower after 6 months |
7. Marcus by Goldman Sachs
Launched in 2016, Marcus by Goldman Sachs is a bank offering a simple, high-yield savings account at 3.90% APY (as of 2026). Their account is appealing with no minimum balance and no monthly fees. Marcus does not offer checking and/or savings accounts with a linked payment system, but focuses on providing different tiers of savings accounts.
The savings accounts are FDIC insured for up to $250,000. Marcus differentiates itself by offering above average APY and by leveraging Goldman Sachs’s brand, capital and licensing to expand its client base.
While its APY is relatively lower than banks like Ally and Bask, it is a stronger bank and institution than those banks. Marcus and SoFi are direct competitors in the high-yield banking space, and Marcus excels due to its strong brand and less complex product offerings.
Marcus by Goldman Sachs Features, Pros & Cons
| Feature | Pros | Cons |
|---|---|---|
| Founded | 2016 | Newer brand |
| APY (2026) | 3.90% | Lower than Ally |
| Minimum Balance | None | N/A |
| Monthly Fee | None | N/A |
| Checking | Not offered | Savings-only |
| ATM Access | None | Transfers only |
| FDIC Insurance | Yes | Standard cap |
| Mobile App | Simple | Fewer features |
| Customer Service | Strong support | No branches |
| Focus | Pure savings | No ecosystem |
| Accessibility | Easy signup | Limited services |
| Yield | Stable | Not top-tier |
8. Synchrony Bank
Established in 2003, Synchrony Bank now offers customers the opportunity to earn a higher yield on their savings. Synchrony offers a high-yield online savings account that has a yield of 3.85% as of 2026. Their high-yield savings account has no monthly fees and no minimum required balance.

Customers of Synchrony Bank are provided the opportunity to access their savings through the Plus and Accel ATM networks. In addition to their savings accounts, customers can also open checking accounts, and CDs and also apply for credit cards.
Like other online banks, Synchrony offers FDIC insurance to ensure the safety of their customer’s funds. With a focus on digital and electronic banking services, SoFi cannot compete with Synchrony in regard to being able to access physical copies of one’s funds.
Synchrony Bank Features, Pros & Cons
| Feature | Pros | Cons |
|---|---|---|
| Founded | 2003 | Mid-age |
| APY (2026) | 3.85% | Lower than Ally |
| Minimum Balance | None | N/A |
| Monthly Fee | None | N/A |
| Checking | Available | Limited features |
| ATM Access | Nationwide + reimbursements | Smaller network |
| FDIC Insurance | Yes | Standard cap |
| Mobile App | Functional | Less advanced |
| Customer Service | Reliable | Digital-first |
| Focus | ATM access | Lower APY |
| Accessibility | Easy signup | Not fintech-level |
| Yield | Competitive | Not highest |
9. Discover Bank
Discover has offered high-yield savings accounts since 1985, with an APY of 3.75% (2026). Their accounts carry no monthly fees or minimum balances. Discover has cash back rewards checking and offers a nationwide ATM network through its checking accounts. The savings accounts are FDIC insured, and the insurance covers $250,000 of each customer’s deposits.

Discover bank is a great option for customers wanting a full service digital bank because of its 24/7 customer service, and because it ties its customer service and credit card systems together. Discover’s APY is lower than Ally’s and Bank of America’s Bask accounts, but Discover is more reputable and has better rewards than SoFi, making it a good alternative to SoFi.
Discover Bank Features, Pros & Cons
| Feature | Pros | Cons |
|---|---|---|
| Founded | 1985 | Established |
| APY (2026) | 3.75% | Lower yield |
| Minimum Balance | None | N/A |
| Monthly Fee | None | N/A |
| Checking | Cashback rewards | Limited APY |
| ATM Access | Nationwide | Some fees |
| FDIC Insurance | Yes | Standard cap |
| Mobile App | Strong | Focused on cards |
| Customer Service | 24/7 | Digital-first |
| Focus | Rewards ecosystem | Lower APY |
| Accessibility | Easy signup | Not top yield |
| Yield | Stable | Below fintechs |
10. American Express HYSA
American Express has offered its High-Yield Savings Account (HYSA) since 2021. The account offers a competitive annual percentage yield (APY) of 3.70% for the 2026 financial year. Current and prospective customers of American Express appreciate that the HYSA has no monthly fees or minimum balance requirements.
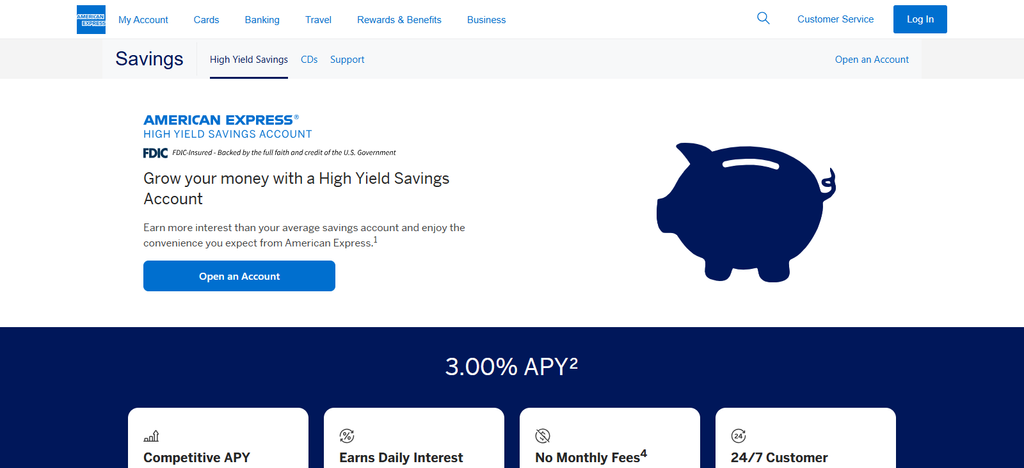
American Express also doesn’t offer checking accounts, and customers of the HYSA can’t use American Express ATMs. As a result, the HYSA is primarily of interest to American Express cardholders, who can earn rewards and other benefits by using their American Express cards.
Each American Express HYSA is FDIC insured for up to $250,000. Strong digital tools and trust in the American Express brand set the HYSA apart from other competitor offerings. Although the APY offered by American Express is lower than some other banks, American Express HYSA is a better alternative to SoFi for existing customers of American Express.
American Express HYSA Features, Pros & Cons
| Feature | Pros | Cons |
|---|---|---|
| Founded | 1850 | Legacy institution |
| APY (2026) | 3.70% | Lowest among competitors |
| Minimum Balance | None | N/A |
| Monthly Fee | None | N/A |
| Checking | Not offered | Savings-only |
| ATM Access | None | Transfers only |
| FDIC Insurance | Yes | Standard cap |
| Mobile App | Strong Amex integration | No ATM |
| Customer Service | Excellent | Limited services |
| Focus | Amex ecosystem | Lower APY |
| Accessibility | Easy signup | Cardholders benefit most |
| Yield | Stable | Not competitive |
Comparison Table – SoFi Competitors (2026)
| Bank/Platform | Founded | APY (2026) | Minimum Balance | Monthly Fee | Checking | ATM Access | FDIC Insurance |
|---|---|---|---|---|---|---|---|
| Ally Bank | 2009 | 4.20% | None | None | Yes | Nationwide + reimbursements | Yes, $250K |
| Bask Bank | 1999 | 4.10% | None | None | No | No | Yes, $250K |
| CIT Bank Platinum Savings | 1908 | 4.10% (> $5K) | $100 open / $5K tier | None | Limited | No | Yes, $250K |
| Western Alliance Bank | 1994 | 4.10% | $1 | None | Limited | Minimal | Yes, $250K |
| Wealthfront Cash Account | 2008 | 4.00% | None | None | No | No | Yes, via partner banks |
| E*TRADE Premium Savings | 1982 | 4.00% (promo 6 months) | None | None | Yes | Partner networks | Yes, $250K |
| Marcus by Goldman Sachs | 2016 | 3.90% | None | None | No | No | Yes, $250K |
| Synchrony Bank | 2003 | 3.85% | None | None | Yes | Nationwide + reimbursements | Yes, $250K |
| Discover Bank | 1985 | 3.75% | None | None | Yes (cashback) | Nationwide | Yes, $250K |
| American Express HYSA | 1850 | 3.70% | None | None | No | No |
Conclusion
Finally, here are 10 SoFi competitors: Ally Bank, Bask Bank, CIT Bank Platinum Savings, Western Alliance Bank, Wealthfront Cash Account, ETRADE Premium Savings, Marcus by Goldman Sachs, Synchrony Bank, Discover Bank, and American Express HYSA. *APYs range from 3.70% to 4.20%. Each bank is FDIC-insured and charges no fees.
Many of these competitors focus on delivering the highest yield while some integrate a checking account or other features. Customers can use these banks to achieve their savings goals while appreciating features such as convenience and peace of mind. When combined, these banks provide various amenities and features and help differentiate from SoFi.
FAQ
Which bank offers the highest APY?
In 2026, Ally Bank leads with a 4.20% APY, followed closely by Bask Bank and CIT Bank Platinum Savings at 4.10%.
Do these accounts have monthly fees?
No. All 10 competitors—including Marcus by Goldman Sachs and American Express HYSA—charge zero monthly fees, making them cost-effective.
Is there a minimum balance requirement?
Most accounts like Ally Bank and Bask Bank require no minimum balance. CIT Bank Platinum Savings requires $100 to open and $5,000 to earn the top APY.
Do these banks offer checking accounts?
Yes, some do. Ally Bank, Synchrony Bank, and Discover Bank provide checking options, while Bask Bank and Marcus focus only on savings.